Exact Instance Compression for Convex Empirical Risk Minimization via Color Refinement
A lossless color-refinement framework compresses convex empirical risk minimization instances exactly, accelerating linear, logistic, and kernel regression solvers.
Published 2026Sydney Poster Session 2 · Tue, Dec 8, 5:00 PM–8:00 PM local time · Hall 1-4arXiv ↗OpenReview ↗
Only vote on papers you've read. Sign in with GitHub to vote.
Abstract
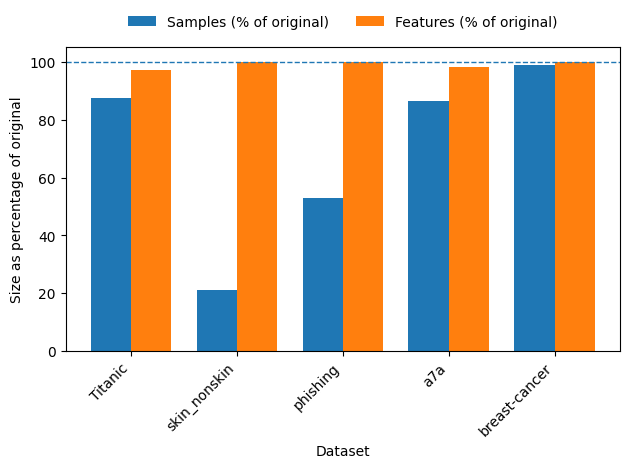
Empirical risk minimization (ERM) can be computationally expensive, with standard solvers scaling poorly even in the convex setting. We propose a novel lossless compression framework for convex ERM based on color refinement, extending prior work from linear programs and convex quadratic programs to a broad class of differentiable convex optimization problems. We develop concrete algorithms for a range of models, including linear and polynomial regression, binary and multiclass logistic regression, regression with elastic-net regularization, and kernel methods such as kernel ridge regression and kernel logistic regression. Numerical experiments on representative datasets demonstrate the effectiveness of the proposed approach.